A budget that explains its reserves
- The executive board must give owners the proposed annual budget.
- It must include a statement of the amount held in reserve accounts.
- It must also state the basis on which those reserves are calculated and funded.
SmartProperty® helps Connecticut HOAs and condominiums plan and fund their reserves. Connecticut doesn’t require a study, but its common interest law requires the board to explain how reserves are calculated and funded, and a study is the defensible way to do that.
The Connecticut Common Interest Ownership Act (CIOA) doesn’t name a reserve study, but it asks the board to back up its numbers.
Section 47-261e asks for the basis on which reserves are calculated and funded. An arbitrary figure fails that test, while a study that analyzes component wear, useful life and replacement cost supports it.
For most Connecticut communities, losing conventional mortgage eligibility is the bigger risk. Fannie Mae and Freddie Mac accept a study less than three years old in place of the percentage test if the budget funds its highest recommended contribution.
Our guide recommends a full onsite study every three to five years and a financial update each year in between, so every annual budget has an accurate basis for its reserve figure.
A site-inspected study to start, then updates as costs and conditions change, so the board always has a current plan.
The Living Reserve Study® updates as projects are completed and costs change, so your plan is ready for the next update or budget.
Model higher contributions, special assessments, loans or lines of credit side by side before you take a recommendation to owners.
Atlas shows the cost data and useful-life assumptions behind every figure, so boards can answer owner questions with confidence.
See how the Living Reserve Study® works for your community, or tell us about your association and we’ll put together a proposal.
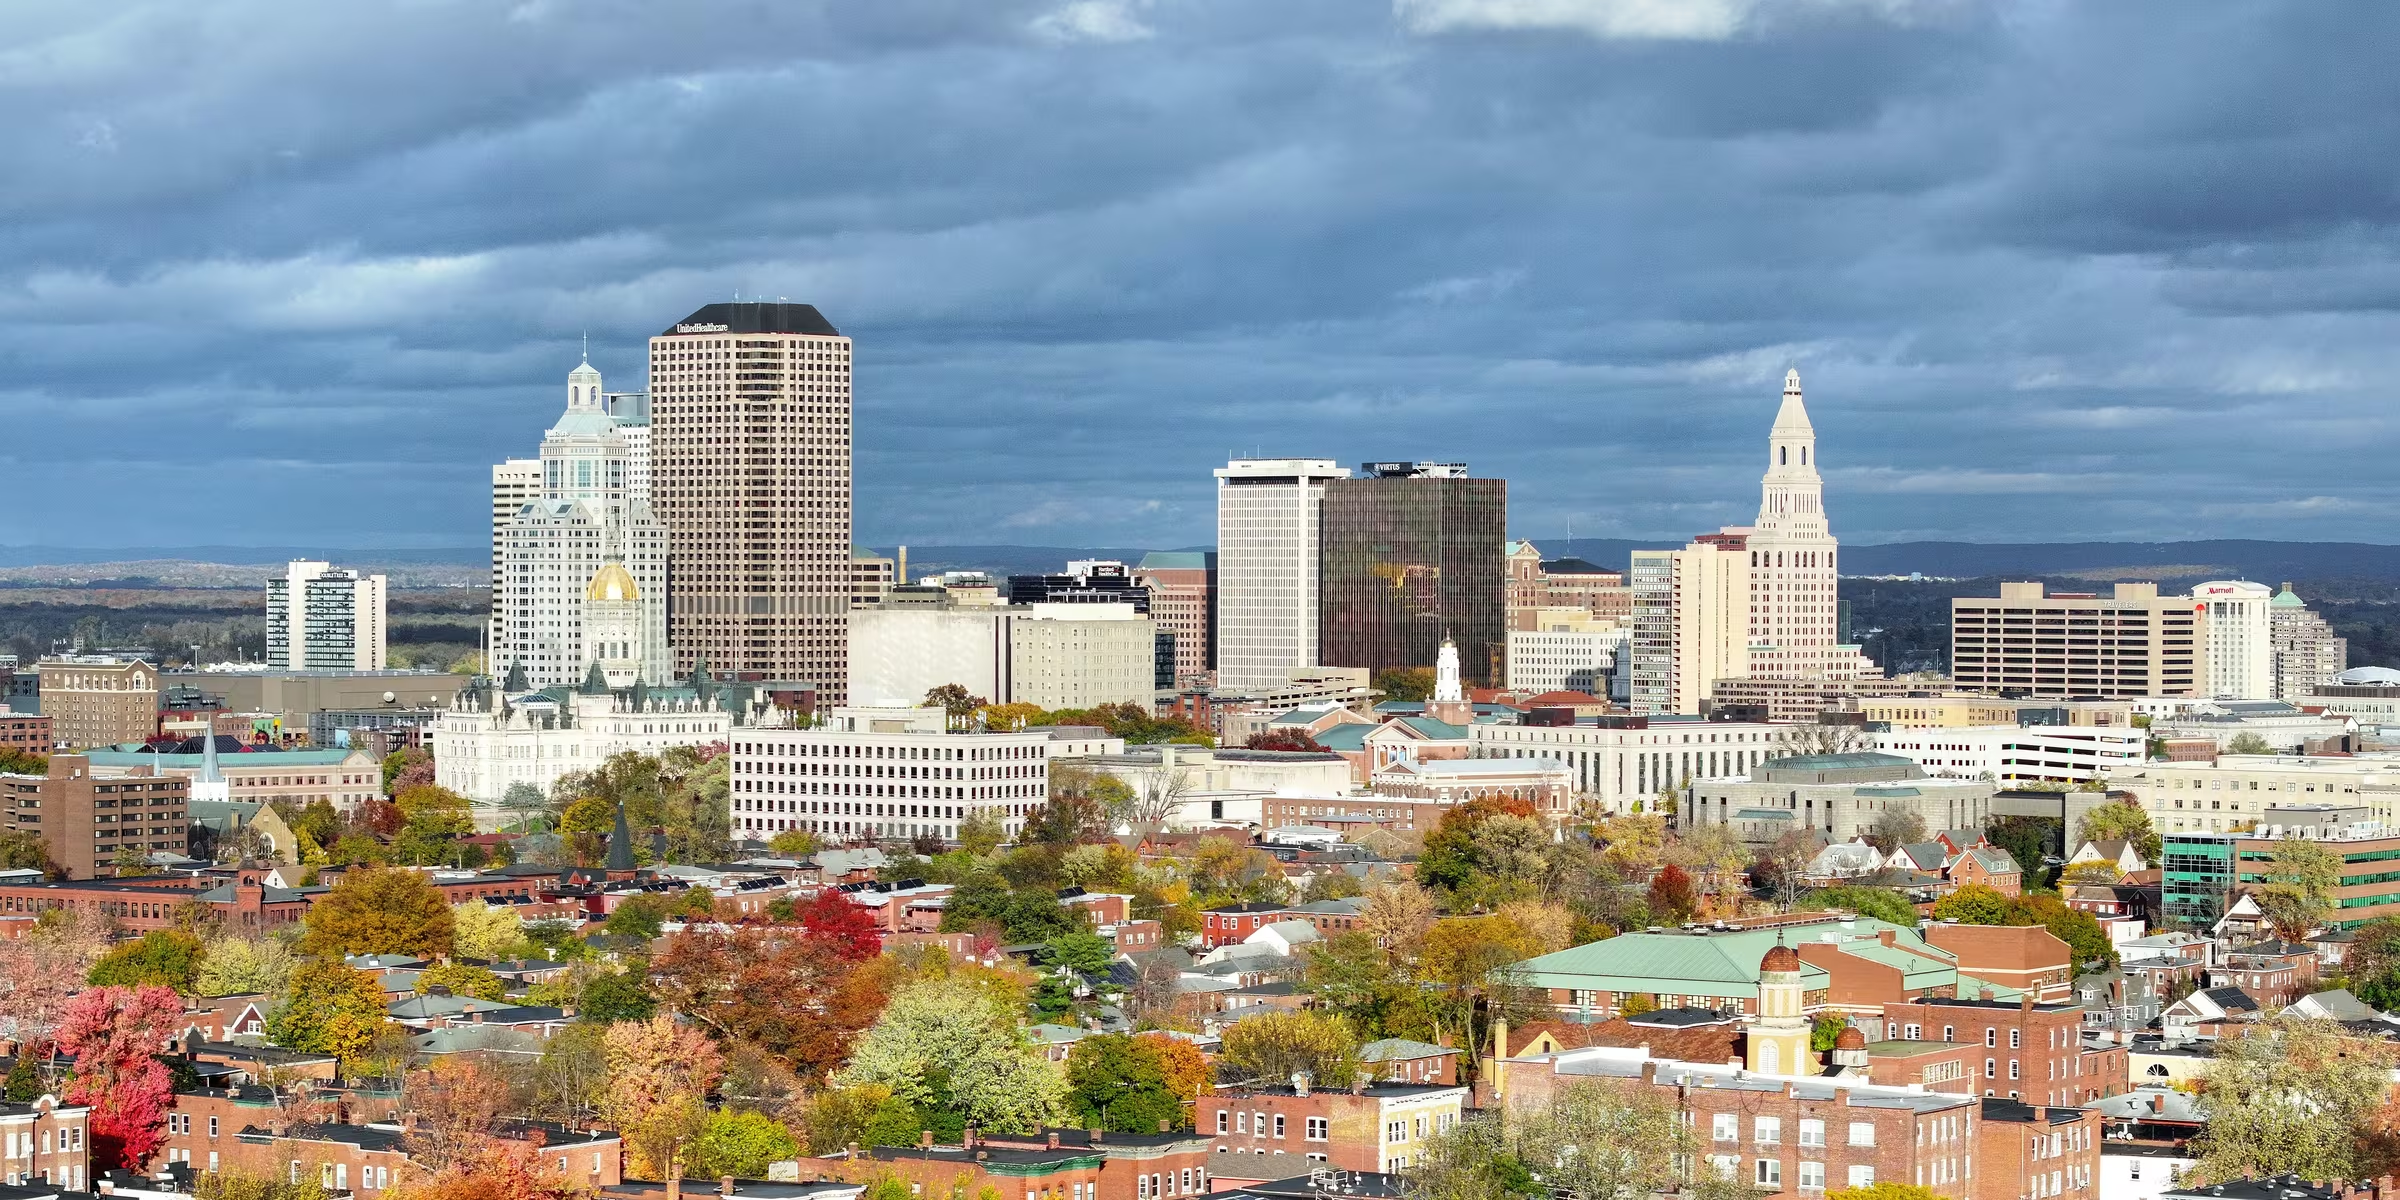
Photo via Wikimedia Commons: Hartford skyline: Quintin Soloviev, CC BY 4.0. Connecticut law summary is not legal advice. Confirm your association’s obligations with Connecticut counsel.